What are credit banks?
In banking, credit banks refer to financial or lending institutions that conduct financial business on a commercial basis. In other words: credit banks grant loans and advances to interested borrowers who need financing.
Often, lending to private and business customers is only one of many tasks credit banks pursue. However, there are also numerous pure lenders. But what fundamentally distinguishes these from other financial institutions?
In Germany, all credit and financial institutions are defined by § 1 of the Kreditwesengesetz (KWG). The term Kreditwesen (credit sector) is only a subset of the broader area of banking. In everyday language, credit institutions and financial institutions are often colloquially called banks or credit banks and frequently equated — but not by the legislator or specialists.
A strict distinction is made here between a pure credit institution and a comprehensive financial institution. The latter is often, for example, the customer’s main bank. As is well known, these institutions also offer — in addition to the ability to open a checking or savings account — various credit options.
Pure credit banks differ precisely at this point, because they usually offer only loans, advances, bonds and the like. In addition, credit institutions can be divided into numerous legal forms: private-law and public-law entities are just the two most common.
A distinction is also often made between direct banks and branch banks. Unlike branch banks, direct banks operate without branches and therefore have no direct customer contact. There are also large banks, which were able to develop by acquiring many small regional banks. Regional banks usually have only a few branches within a region. Branches are an additional office of a company (here a regional bank) and are usually assigned to a main office. The branches of a bank are centrally managed by the main office. As the name suggests, regional banks and their branches are therefore only found within a specific region.
Bank loans and other types of credit
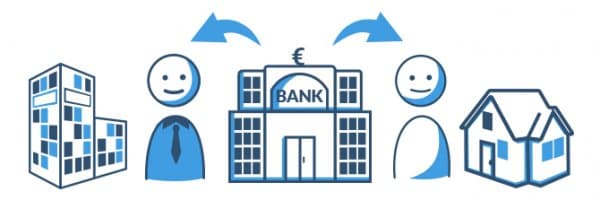
Almost all loans are bank loans; the brokerage of private loans as well as borrowing from a pawnbroker account for only a small portion of the total credit volume.
In most cases, dealer-financed purchases are also bank loans, since the dealer forwards the customer's loan application to credit banks.
Genuine dealer loans, where the seller provides the financing itself, do exist in the form of installment agreements (/en/installment-loan), but compared with bank loans brokered by retailers they are rare.
In addition to credit banks, life insurers can also act as lenders; they can lend against policies taken out with them and grant construction loans (mortgage financing). Mortgage financing can be used exclusively to finance a property or a construction project. It also covers ancillary building costs and offers favorable terms. These favorable terms are possible for the bank because the property being financed is regarded as collateral.
The distinction commonly used in public discourse between an internet loan and a bank loan is neither legally nor factually justified, since a loan granted over the Internet is handled by credit banks in the same way as a loan application in a bank branch.
The business of money: the history of credit banks
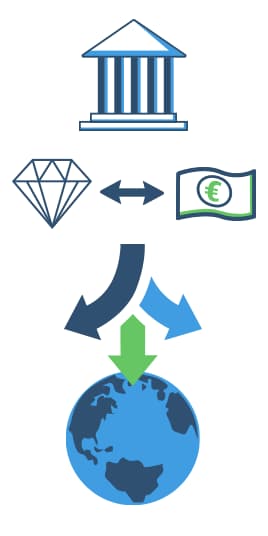
Looking back at the long history of the broader banking system, one can see that the credit bank and the main bank were not so dissimilar in earlier times. The era of credit banks began broadly with money becoming increasingly popular and commonplace as a means of payment. This is where the first original "banks" came into play, taking on many tasks related to trading coins and more.
On the one hand, they accepted valuable goods such as jewelry and gold to exchange them into coins. At the same time, as early as the second century AD it is documented in various countries, such as Mesopotamia, that credit-like loans were made. These were of course always dependent on collateral such as land and were therefore reserved more for the wealthy than for the poor.
Banking business reached Europe only in the 14th century. The first banks spread in Italy from Florence, with attention immediately focused on the poorer population groups. The wealthy of the cities, however, nourished the banks and were rewarded with interest-like repayments.
The modern form of credit as such was thus born in Europe. Germany took a bit longer and established the first banks for the general public in the 18th to 19th centuries.
In Europe, banking also first took other forms in the 19th century: reserves and saving. The first savings banks were founded and offered people the opportunity to invest their money profitably; for example, to secure themselves in old age or for other eventualities such as illness.
At the same time, financial institutions began to work with the deposited money, which ultimately gave rise to a new form of credit. After all, people wanted to make the money they had put to work earn even more money. At that time there were countless public-law as well as independent and private financial institutions.
To prevent these institutions from freely using deposited funds, the legislator intervened and attempted with the first drafts of the monetary law in 1934 to restrict bankers and private banks so that they could use only small portions of the stored sums. The credit legislation known today was introduced in 1962. Since then it has of course been modernized, improved and optimized several times.
Functions of credit banks
Looking at the history of banking and the associated credit sector, it becomes clear where the main task of a credit institution lies: it primarily exists to grant and enable loans to borrowers.
In technical terms, they have the economically important function of intermediation. More plainly, this means they are responsible for the functioning of money and capital flows. This broadly concerns both cash and non-cash payments. That means credit institutions by no means only have the role of simply handing money over to borrowers.
Numerous other tasks take place behind the scenes of the credit sector. Some of these include processing payment transactions, accepting interest-bearing deposits, supplying private and business customers with loans and advances, and handling the extensive securities and issuance business across Europe and often beyond European borders.
Credit institutions and their various types and legal forms
A credit institution, as already indicated, is by no means like another. There are significant differences, most evident in the various legal forms. This is because the definition of credit banks as such is only marginally restricted by law — there is no single form the law prescribes for differentiation.
Therefore, a credit institution can, for example, be a company organized under private law or also run by a legal person under public law. The difference here lies in small but important details, which often confuse and unsettle private individuals.
Broadly speaking, there are various forms of private-law companies that can operate in the credit sector: sole proprietorships run by a single banker, registered cooperatives, partnerships such as general partnerships (OHG), limited partnerships (KG) or GmbH & Co. KG, as well as corporations.
These in turn include joint-stock companies in the form of the European company, partnerships limited by shares (KGaA) and also limited liability companies.
Special credit banks
Nowadays, most credit institutions operate in the legal form of an institution under public law. In many cases, several banks or companies join together to form a credit institution.
Examples include credit banks set up jointly by a car dealership and a credit or financial institution to make it easier for dealership customers to buy a new car through financing. If these start well, they are often detached from their founding area sooner or later, so that customers can apply for an installment loan from these credit banks even without purchasing a car.
Comparing credit banks
The different offers from credit banks differ not only in interest rates but also in other loan agreements or conditions. Borrowers can easily determine the least expensive bank loan — for which the repayment terms remain unchanged compared with the original agreement — by comparing the effective annual interest rate (/en/topics/loan-comparison).
All costs associated with taking out the loan are included in the effective annual interest rate. These include the installments that must be paid each month, but also one-off costs such as fees. A credit default insurance, however, must only be included in the effective interest rate if the insurance is a prerequisite for receiving a loan.
In addition to the effective annual interest rate, it is advisable when comparing loans to consider the loan conditions of the individual credit banks. These differ primarily in terms of the possibility to change the repayment agreement if needed or desired.
The nominal interest rate is also important for the loan decision, as it is decisive for recalculation after a changed repayment agreement.
Possible costs at credit banks
- While some credit banks already charge high fees for changing the payment period, other lenders offer changes to the repayment rate as well as a payment suspension (also called a payment holiday) once per year free of charge. Therefore, borrowers should inform themselves in advance whether a payment holiday or other change requests may incur high costs.
- Early repayment is generally permitted for private borrowers; however, credit banks may demand compensation for their loss of profit if the loan agreement does not entitle the borrower to fee-free early repayment.
Submitting a loan application to credit banks can sometimes make sense
The processing effort for a loan application is lower compared with a personal application in a bank branch if the prospective borrower fills out the form on the Internet. Credit banks transfer money to their customers in electronic form, so loans applied for over the internet are often cheaper than loans agreed in a branch. Nonetheless, a personal visit to a bank branch can sometimes be advisable.
Even with existing negative Schufa entries, a successful loan application with German credit banks is possible. This applies especially if the entry is old and the borrower's financial situation has changed due to subsequent employment. Because online loan applications are often processed automatically, older Schufa entries are sometimes grounds for rejection, whereas in a personal conversation approval of the loan may be obtained.
Alternatively, you have the option of applying for a so-called Kredit ohne Schufa (loan without Schufa). A Schufa-free loan (/en/topics/instant-loan-without-schufa-2) is mainly offered by credit banks from Liechtenstein and Switzerland, whereby they usually require a clear minimum income for granting the loan. These loans are also suitable for borrowers who do not want their borrowing to be registered with Schufa.
Wide range of offerings from credit banks
Consumers today face the dilemma that there is an oversupply both within Germany and among foreign providers. While this offers the opportunity to choose, it also requires a thorough examination of individual credit banks and their loan offers and financing conditions.
Whereas the main bank used to be practically the only address, today there are countless loan offers. This can lead to a feeling of disorientation, but the consumer has the advantage that much information is available on the internet.
This can be a path through the jungle of banking if one uses it. Of course, this involves more effort, but if you want to be sure after taking out a loan that you are saving money and getting real bargains, the effort is worthwhile to find the right bank for an installment loan.