Equity
The term equity is used in different situations. It is particularly important in the context of accounting and financing of companies. In addition, the word equity is also used when private individuals take out mortgage financing. This article aims to explain the different meanings of equity in more detail. It also provides explanations of the most important functions of equity and the relationships with other decisive factors.
What is equity?
At first glance equity may seem self-explanatory, since it actually describes the portion of financing that the debtor funds from their own resources. Nevertheless, a distinction must be made here between the meaning in company accounting and the use of the term in mortgage financing:
1. Equity as an item in a company's balance sheet
In this context, equity describes the difference between a company's assets and liabilities. It is the only balance sheet item that cannot be measured directly but is determined as a residual figure. Simplified, a company's balance sheet looks as follows:
Balance sheet of company XY as of 31.12.20xx
| Assets (source of funds) | Liabilities (use of funds) |
|---|---|
| Fixed assets (e.g. land, machinery, vehicles, licenses and patents, investments) | Equity (net assets) |
| Current assets (e.g. inventories, receivables, securities, cash and cash equivalents) | Debt (liabilities) (e.g. bank loans, trade credit, provisions, other liabilities) |
| Total assets | Total assets |
In accounting, all items except equity can be determined precisely in advance and entered in the balance sheet. Since the totals on both sides of the balance sheet must be equal, equity is the residual between the asset values on the asset side and the debts (liabilities) on the other side.
Note: If a company's equity is negative, it is shown on the asset side. In this case, the company's liabilities exceed its assets. For corporations, negative equity typically triggers insolvency due to over-indebtedness.
How does equity arise in a company?
When a company is founded, the shareholders contribute equity in the form of cash contributions or contributions in kind. Contributions in kind can, for example, include real estate or land. The legislator prescribes a minimum capital for corporations.
Stock corporation (AG): Minimum capital €50,000 (§7 Stock Corporation Act)
Limited liability company (GmbH): Minimum capital €25,000 (§5 GmbH Act)
In addition, there are other ways for a company to increase its equity:
- Capital increase: More capital is provided by shareholders and investors. This can be achieved either by increasing the contributions of existing shareholders or by gaining new shareholders. In many cases, existing shareholders of an AG have a pre-emptive right (subscription right) to purchase new shares to maintain their stake.
- Retained earnings: Part of the annual surplus is retained and recognized in revenue reserves.
- Recognition (activation) of assets: New assets are capitalized on the balance sheet. This can happen not only through an asset swap (cash for assets = purchase) but also by a shareholder contribution. In addition, accounting options can be exercised and internally generated intangible assets or low-value assets can be recognized.
- Revaluation of assets or liabilities: By exercising valuation options, assets can be revalued higher or certain types of liabilities lower, depending on the situation. This also leads to a change in equity.
What components does equity in a company consist of?
A company's equity consists of various subcomponents in the balance sheet. These individual components are explained in more detail below:
Subscribed capital
Subscribed capital is the part of equity to which the liability of the shareholders of a corporation is limited. The rules on minimum capital at formation apply to equity. Typically, subscribed capital is formed by shareholder contributions and later capital increases. An increase from company funds is also conceivable. The term "subscribed capital" is named differently depending on the company form:
- Registered capital (AG)
- Share capital (GmbH)
- Limited partner capital (KGaA)
- Business credits (eG)
Capital reserves
Capital reserves are part of the statutory reserves and, according to §272 para. 2 HGB, consist only of the following positions:
- Premiums from the issuance of shares (both shares and bonds, convertible bonds and options)
- Amounts from additional contributions by shareholders against preferential rights
- Further contributions by shareholders
Revenue reserves
Revenue reserves are formed from undistributed annual profits and can be divided into the following areas:
- Statutory reserve: Stock corporations and partnerships limited by shares must build this reserve to protect creditors. For this purpose, 5% of the annual surplus (reduced by prior-year losses) must be allocated to the revenue reserve each year until this reserve together with the capital reserve equals 10% of the registered capital.
- Reserve for “shares in a controlling or majority-owned company”: This reserve is the counterpart to the shares on the asset side. If such shares are sold, the reserve must be dissolved accordingly.
- Statutory reserves: If the articles of association of a stock corporation provide for the formation of further reserves, these can be created.
- Other revenue reserves: Remaining amounts not covered by the other types of reserves.
Profit carried forward
Since profits must not directly affect the subscribed capital of a corporation, the profit carried forward functions as a variable equity account. If an unused profit is shown, the profit carried forward ensures that the next financial year starts with a profit balance.
Loss carried forward
This is the counterpart to the profit carried forward. If an annual loss is not offset by equity or shareholder payments, the loss carried forward can be transferred to the following year under certain conditions. It may then be offset against profits in subsequent years.
Retained earnings
Retained earnings are a residual item of equity that remains after offsetting the annual surplus with profit and loss carryforwards, withdrawals, and capital and revenue reserves. Retained earnings are then paid out to shareholders as dividends.
What are the differences between equity and debt?
At first glance, the distinction between equity and debt may seem simple. In practice, however, it is often not so straightforward. There are nevertheless some characteristics that can be attributed to the two types of capital:
Equity:
- Repayment can depend on the company's success
- Return depends on the company's success
- Equity tends to grant participation rights in the company
- In insolvency, equity bears the liabilities of the company
Debt:
- Obligation to repay
- Return is independent of success and is agreed in advance
- In insolvency, debt is repaid in part or in full according to the available insolvency estate
While the classification is clear in cases of shareholder contributions (equity) and bank loans (debt), there are also hybrid cases. Such capital types are referred to as mezzanine capital, which is partly classified as equity and partly as debt. These include:
- Hybrid bonds (very long term, subordinated in insolvency)
- Loans from shareholders (formally debt, but subordinated in insolvency)
- Contributions from silent partners (more like debt, but may include loss participation)
- Subordinated loans (debt, but subordinated in insolvency)
- Participating rights (very differently structured depending on the case)
2. Equity in mortgage financing
The definition of equity in mortgage financing is much easier to grasp. It simply refers to the borrower's own share of the costs for purchasing a property or for construction. A simple example illustrates this:
Purchase price of a property = €200,000
Equity = €50,000
Loan amount = €150,000
Equity share = 25%
Equity in mortgage financing - what to consider?
In mortgage financing, equity that borrowers can contribute is always one of the important parameters alongside other factors. For laypersons, this topic raises many questions, which are answered below:
Why is equity important in mortgage financing?
Anyone who wants to buy or build a property usually needs mortgage financing. Because mortgage loans often involve very large sums and long terms, banks and other lenders require appropriate collateral for granting the loan. This collateral is intended to ensure that the lender does not have to write off the money lent in the event of payment difficulties. If this situation occurs, the collateral is realized and the bank recovers a large part of the outstanding amount. The property itself serves as the main collateral in mortgage financing. It is an asset and is secured by a land charge (Grundschuld). To clarify the importance of equity in mortgage financing, the collateralization process must first be explained in more detail. The current purchase price of a property is the so-called market value. Since this fluctuates and depends on current market conditions, it is not used as the basis for the level of collateral. Instead, banks focus on other metrics:
- Lending value (Beleihungswert): The lending value represents the value that can sustainably be achieved through a resale of the property, independent of short-term fluctuations. This is typically between 75% and 90% of the purchase price and represents the absolute upper limit of lending.
- Loan-to-value ratio (Beleihungsauslauf): The loan-to-value ratio is a quotient that indicates the actual lending in relation to the lending value. It is calculated as follows:
- Loan-to-value = (loan amount + prior charges) / lending value A conventional mortgage usually starts at a loan-to-value of 60–80%. Of course, there are also mortgage financings without equity where 100% or more of the loan-to-value is chosen. These are only possible and sensible in exceptional cases.
Without equity, it may therefore happen that mortgage financing is not possible at all or only on very poor terms.
How much equity should you put into mortgage financing?
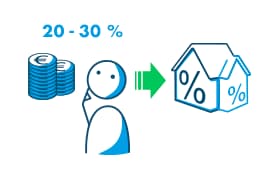
As a rule, you can never have enough equity for mortgage financing. A high equity share has several effects:
- Lower interest rates
- Shorter term and lower loan amount
In practice, an equity share of 20–30% of the purchase price has proven to be very sensible. This makes it possible to obtain favorable interest rates and tailored mortgage financing.
What counts as equity in mortgage financing?
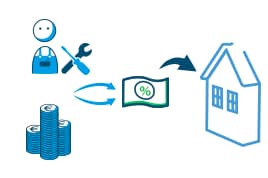
Equity in the context of mortgage financing primarily consists of monetary funds with which borrowers can already pay a portion of the purchase price. This reduces the loan for the property and significantly improves the lending situation. In addition, home improvement or construction work carried out by the owner can also be recognized as equity. This is particularly the case in house construction. Typical owner-performed work that may be credited as equity includes:
| Owner-performed work | Requirement | Possible savings |
|---|---|---|
| Wallpapering / painting | Although these tasks require some skill, they can be done satisfactorily without professional training. | €3,000 - €4,000 |
| Thermal insulation | Certain knowledge is required, but execution by a competent DIYer is possible. | €5,000 - €6,000 |
| Installation of doors | Internal door frames and doors can also be installed by the owner. | €3,000 |
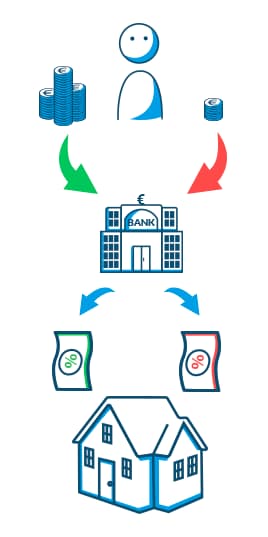
As a rule, banks recognize owner-performed work up to 15% as equity in mortgage financing. Nevertheless, equity cannot be completely replaced by owner-performed work, only supplemented at best. Owner-performed work also has other disadvantages:
- No guarantee by professionals
- No insurance coverage for amateur work
- High time expenditure alongside regular employment
Does the amount of equity affect the interest rate of a mortgage?
The interest rate for a mortgage depends on numerous factors. Equity, however, is one of the biggest influencing factors on mortgage rates. As already explained, a loan for real estate is secured by the lending on the property. By registering a land charge in the land register, a bank could recover a substantial part of the outstanding amount via forced sale in the event of borrower default. This leads to the following relationships:
More equity → lower lending ratio → higher collateralization of the loan → lower default risk for the bank → lower interest rates for the mortgage
Banks usually reward a lower default risk with more favorable interest rates. Thus, the terms of a mortgage can often be significantly improved by contributing one's own funds.
Mortgage financing without equity - is that possible?
Although 20–30% equity is usually considered the basis for property financing, there are exceptional ways to finance. Mortgage financing without equity can be divided into two categories:
- 100% financing: The full purchase price of a property is financed through a bank. Ancillary costs such as transfer tax, notary fees and broker fees are paid from own funds.
- Full financing: Full financing includes, in addition to the full purchase price, the ancillary costs of acquiring the property.
What requirements must the borrower meet for mortgage financing without equity?
Because lending on the property in a mortgage financing without equity significantly exceeds the lending value as an upper limit, this is a very risky financing. For this reason, borrowers must meet special requirements to obtain such a loan:
- Exceptional creditworthiness: While a clean SCHUFA report is essentially mandatory, the borrower's scoring value should also be as good as possible.
- High and secure income: Without equity, the loan amount is very high. Therefore, borrowers must be able to service high repayment amounts with their income. Income security is also important.
- Location and condition of the property: The desired property should be in an up-and-coming location and in good condition. Otherwise, devaluations may occur during the term and put the entire financing at risk.
Do you have to pay a higher interest rate for property financing without equity?
The lack of equity in full financing is a clear shortcoming in terms of collateral. Higher risk generally means worse terms from banks. Therefore, borrowers must expect a higher interest rate with mortgage financing without equity.
When is mortgage financing without equity sensible?
The essential peculiarities of mortgage financing mean it is by no means affordable or attractive for every borrower:
- Longer term
- Higher loan amount
- Greater debt risk in the event of default
This is illustrated by the following example:
The purchase of a property for €220,000 is carried out once with 30% equity and once completely without equity. The fixed nominal interest rate is 2.50% in the first case and 4.00% in the second case. This results in the following parameters:
| Loan A (30% equity) | Loan B (no equity) | |
|---|---|---|
| Loan amount | €154,000 | €220,000 |
| Fixed nominal interest | 2.50% p.a. | 4.00% p.a. |
| Initial repayment | 3% | 3% |
| Monthly payment | €705.83 | €1,283.33 |
| Term | 15 years | 15 years |
| Total interest costs | €43,072 | €95,650 |
| Remaining debt after 15 years | €70,022 | €84,650 |
| Difference (interest costs) | €52,578 |
Mortgage financing without equity results in a higher monthly repayment rate, higher interest costs and also a higher remaining debt after the fixed interest period expires. Therefore, it is only suitable for the following groups of people:
- Young and high-earning persons who can afford high repayment rates.
- Civil servants in senior positions with correspondingly high incomes.
- Persons with invested assets that yield a higher return than mortgage interest rates.
Those who are willing to take high risks and to repay large sums quickly may find mortgage financing without equity appropriate. However, even small income setbacks can lead to payment difficulties, and without equity it can happen that a forced sale yields less than the outstanding debt. Affected parties would then lose the property and still owe a remaining amount to the bank.
Equity - A brief conclusion
Equity is an important metric for companies and also in property financing. In the business sense, it describes the difference between assets and liabilities in a balance sheet. The equity ratio indicates the proportion of equity in total capital. In mortgage financing the basic principle remains the same, but here it only concerns the share of own funds in the total costs of the financing. The higher the equity, the easier it is for borrowers to obtain a loan for building or buying a property. In addition, equity has a favorable effect on the interest rate of a loan.