Meaning of loan interest
A loan is the granting of credit by a bank, insurance company or savings bank, for example for mortgage financing or the purchase of goods.
For a loan, lenders — i.e. the credit institutions — demand monthly repayments and, of course, interest, which together with the repayment are paid monthly by the borrower. The loan interest can be understood as the price banks charge for granting the loan.
Loan interest: costs of a loan
As mentioned, the costs of taking out the loan and the repayment instalments must be paid monthly. It is therefore important to look for the most favourable terms possible before concluding loan agreements with a lending institution.
The loan interest rate is particularly important here. You should look for a lender who is on the one hand known as a solid institution and on the other hand charges the lowest possible loan interest rates.
Creditworthiness and loan interest
"Creditworthiness" refers to a buyer's/customer's financial ability to repay a given loan. Many banks therefore check via Schufa whether the borrower has sufficient financial strength to cover the repayment of the loan and the payment of the loan interest. A positive Schufa score is therefore an essential factor for obtaining a loan in Germany.
However, there are institutions that dispense with a Schufa report and still offer favourable loan interest rates. For example, one can also obtain reports abroad (e.g. in Switzerland) to see whether convincing possibilities exist there to obtain a loan — this may be worthwhile in the long run.
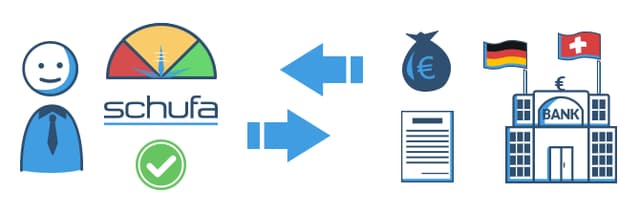
Therefore, it can be assumed that all social groups, including those who do not feel financially strong enough, have a chance of obtaining a loan. In any case, you should not let fear of taking out a loan stop you from applying for credit because you are too worried about a Schufa check by the lending bank. As mentioned, there are reputable lenders who forgo such checks and still provide the necessary funds. A comparison of the different providers is possible on the internet via various portals. Here you can compare factors such as the effective interest rate or the loan amount.
Determination of loan interest rates
The European Central Bank (ECB) sets the key interest rates monthly. Since banks borrow funds there themselves, they orient the loan interest rates they charge to borrowers to these key rates. As everyone knows, the ECB's key interest rates have been very low since the last economic crisis — therefore the loan interest rates (for example mortgage rates when buying a house) that banks or savings banks grant are comparatively at a very low level.
Loan interest rates naturally also depend on the term of the loan, which means, for example, that a loan with a five-year fixed-interest period will be cheaper than one with a ten- or fifteen-year term. To achieve long-term stability of your finances, it is generally advisable to aim for as long a fixed-interest period as possible.
Fully secured loans are cheaper
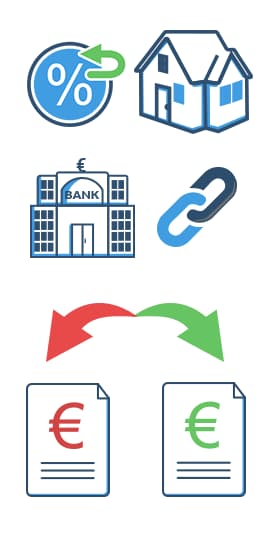
The interest rate for loans also depends on collateral. This aspect can be observed very well with construction loans. In the context of long-term mortgage financing, consumers have to pay high interest rates for loans if the financing is not fully secured.
Collateral also often has a strong influence on personal loans. Personal loans that are not fully secured are granted on higher terms. For loans that are completely secured, the interest rates will accordingly be lower.
An exception here is the overdraft facility. For an overdraft, the interest rate normally does not change due to the collateral. The interest rates for loans can also increase when taking out a loan if the prepayment options are particularly extensive.
If there are high prepayment options, lending institutions always face the risk that borrowers will repay loans early and thus the margin will be very small. For this reason, interest rates for loans are increased in these cases.
A comparison of the effective interest rate depending on security and special conditions is therefore recommended. This way you as a borrower can better weigh your options. How large is the difference in interest and fees if prepayments are possible versus if they are waived? Are the additional costs worth this option? For mortgage financing, for the same reason, it pays to compare mortgage rates. For a rate comparison you can request offers with different securities.
However, it is important that you always compare offers from different providers under the same conditions.
How can consumers influence loan interest rates?
Consumers can of course influence loan interest rates through their own creditworthiness and collateral. Many applicants, however, have poor creditworthiness and cannot provide collateral. But even these people have a good opportunity to influence the terms for their loans. There are now many companies on the internet that offer loans for small amounts up to mortgage financing.
All consumers have the opportunity to search the internet for affordable loans. When looking for low loan interest rates, applicants should always perform a loan comparison. With a loan comparison users can find the cheapest offers. When comparing, both the interest rate and the offered terms should be taken into account.
Even consumers with poor Schufa can in this way obtain very favourable loans. Fundamentally, every consumer has the chance to take out attractive loans.
Conclusion – low interest rates for loans
Overall, it can be said that the fear of high interest rates is unfounded. The current market situation enables low loan interest rates like never before. Borrowers should therefore not be afraid of loans such as mortgage financing and should not shy away from the interest rates if they aim to own property.